Your Local Mortgage Lender
Located in Edina, Minnesota
Personalized Mortgage Experience
Alex Mysinek offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Edina, Minnesota.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
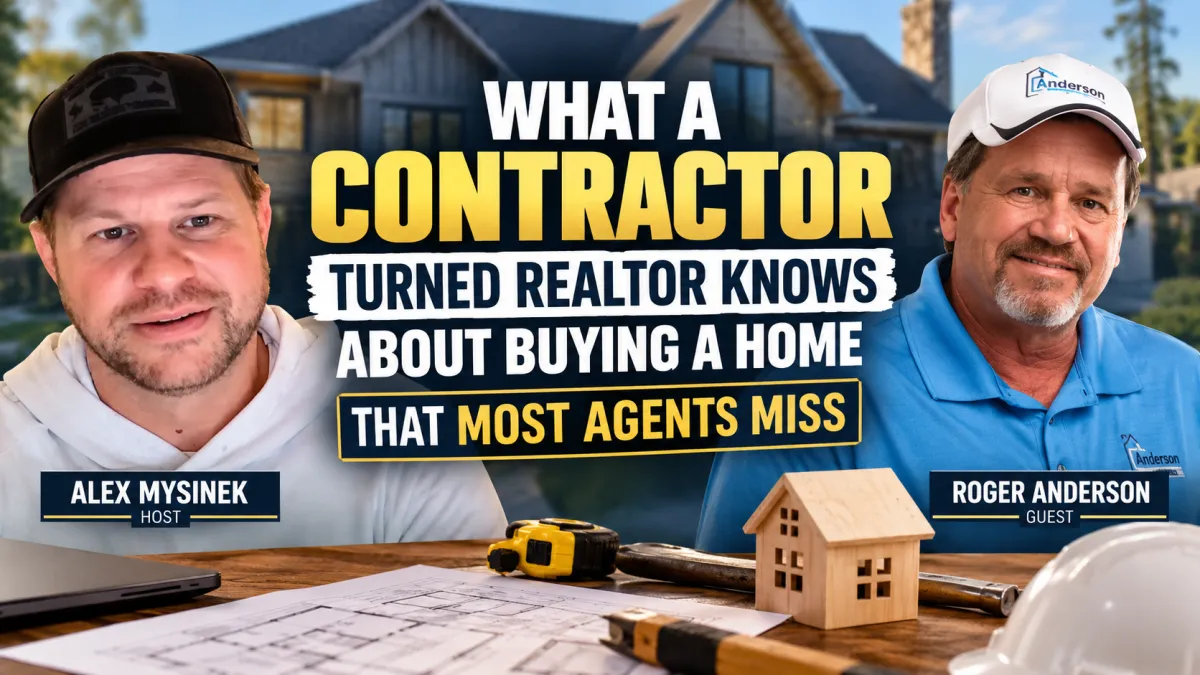
Beyond the Listing: Alex Mysinek Talks Construction Secrets and Home Buying Pitfalls With Roger Anderson
The Realtor Who Has Been in the Construction Trade Since He Was Eight Years Old
Alex Mysinek sat down with Roger Anderson, owner and broker of Elite Realty Minnesota, for a conversation that goes places most real estate podcasts never reach. Roger is not just a realtor. He is a licensed general contractor since the late eighties who has built over twelve hundred homes and remodeled countless more. Six uncles, both grandfathers, and his father were carpenters. He was swinging a hammer before most kids were riding bikes without training wheels.
He got into real estate not by design but by necessity. When the housing crash hit in 2006 he could no longer afford to pay the realtors working with him and had to get licensed to sell his own inventory. Minnesota law requires a real estate license after twenty-five transactions anyway. He has been bridging the gap between construction knowledge and real estate representation ever since.
What His Construction Background Actually Does for Buyers
Most buyers spend five hundred to a thousand dollars on a home inspection and then receive a report that either scares them unnecessarily or misses the things that actually matter. Roger's value to buyers operates at a different layer entirely.
He walks through properties looking at what he describes as fit and finish and code. Not colors. Not carpet. Not staging. He is assessing the roof, the plumbing, the electrical, the mechanicals, the foundation, and everything that determines whether the house is sound and safe to live in rather than whether it photographs well.
His ability to identify a problem on the first walkthrough changes the entire dynamic of a purchase. A buyer who walks into a home inspection already knowing the significant issues is in a completely different position than one who discovers them for the first time from an inspector's report. The negotiation about those issues happens from a position of knowledge rather than surprise. And the deals that should not proceed get identified before anyone spends seven hundred dollars to confirm what Roger already saw.
He is also clear that he is not diminishing agents who do not have his background. He acknowledges openly that most agents simply do not have construction experience and that buyers should be thoughtful about who they choose to represent them. Passing a real estate exam does not make someone an expert on homes. He teaches his agents the basics of how a home is built and why because he believes that knowledge is part of what they owe their clients.
What Looks Scary but Actually Is Not
Roger identifies the mechanical room as the single biggest source of unnecessary buyer panic. Do-it-yourself plumbing and electrical work that does not meet code can look alarming in an inspection report even when the underlying systems work perfectly well. An inspector's job is to identify everything that is not to code and they do it thoroughly. But the bedside manner of how those findings are communicated can unravel deals that should never have come apart.
Window fogging from a failed seal. A door that needs adjustment. Vacuum breakers on hose bibs. A crack in a window. These are items that inspectors flag and buyers sometimes treat as catastrophic when the actual repair cost might be fifty to a hundred dollars. Roger has watched deals collapse over lists of minor items where the total fix cost was under a thousand dollars.
His point is direct. An agent who does not know the difference between a code issue that represents a safety concern and a code issue that represents a five-dollar part being installed incorrectly cannot properly advise a buyer on whether to walk or stay. That gap in knowledge is where deals die unnecessarily and where buyers lose homes they should have purchased.
The Mold Conversation Most People Are Having Wrong
Roger tackles the mold question with the same practical framework he brings to everything. There are approximately a million types of mold. Only three are genuinely harmful to humans. Mold requires three conditions to survive: no sunlight, moisture, and a food source. Remove any one of those conditions and it cannot survive.
Water intrusion in a basement corner that looks alarming to a buyer might be a grading issue outside the foundation. It might be a disconnected downspout. It might be a gutter falling away from the fascia. It might be a fifty-dollar fix. The word mold triggers fear that is not always proportionate to the actual situation.
He also raises something most buyers do not know. Waterproofing basements was not common industry practice until the eighties and was not required by code until 2002. Any home built before that threshold was not waterproofed as a code requirement. Finding evidence of past moisture in an older basement is not automatically a sign of a compromised structure. Context and knowledge determine what it actually means.
New Construction Versus Existing Homes: The Real Comparison
Roger has built over twelve hundred homes and he gives new construction an honest assessment rather than a promotional one.
Every new construction home should have an independent inspection regardless of the fact that it is brand new. City inspectors run multiple people through a new build at different stages covering plumbing, electrical, and framing separately. Things still get missed. Handrails. Fit and finish items. Systems that were supposed to be completed and were not quite finished at inspection time. An independent inspector provides a second set of eyes and an independent voice that is not employed by the builder.
He also raises something from his own builder experience that stuck with him. At a new construction walkthrough the builder's agent could not tell the buyer where to install the furnace filter. Roger ended up doing the mechanical walkthrough himself. She later asked him to come back and videotaped it so she could use it for future clients. This is the gap his background fills.
The actual cost comparison between new and existing is more nuanced than most buyers realize. Take a three hundred thousand dollar new build versus a two hundred and seventy-five thousand dollar existing home that is twenty years old but has a newer furnace and water heater. The existing home still has an aging roof, aging systems, and deferred maintenance items waiting to emerge. A trip or two to the home improvement store adds up fast. The twenty-five thousand dollar price difference evaporates quickly when you start accounting for what the older home will eventually need.
On the other hand new homes built between 1984 and 2002 represent an era Roger describes as the worst period in residential construction. The government tightened building envelopes in response to the 1970s energy crisis without fully accounting for indoor air quality. Homes built in that window were sealed more tightly than homes before them without the ventilation systems needed to handle the resulting moisture and air quality issues. Since 2002 code has addressed indoor air quality and continues improving every three to four years. A home built today is meaningfully better in terms of energy efficiency and indoor air quality than a home built in 1995.
What Elite Realty Minnesota Offers Agents
Roger runs Elite Realty as a hundred percent commission brokerage and is direct about why. Every dollar he keeps from an agent's commission is a dollar that agent cannot spend on advertising, marketing, and building their own business. He sees his role as partner rather than the logo on the card. His philosophy is standing alongside agents rather than in front of or behind them.
He provides broker and owner support seven days a week. He pays agents the day they close rather than making them wait weeks after closing to receive their commission. And every week he teaches his agents the basics of how a home is built and why because he believes that knowledge is what agents owe the people who trust them to navigate the largest financial decision of their lives.
If an agent is looking at joining a brokerage that invests in their knowledge and treats their commission as theirs to keep reach out to Roger directly.
How to Reach Roger Anderson
Call or text 612-369-7281. Email [email protected]. He answers seven days a week and welcomes conversations with buyers, sellers, and agents interested in learning more about Elite Realty Minnesota.
Alex Mysinek works with buyers throughout Minnesota on mortgage financing including conventional loans, down payment assistance programs, and investment property products. Reach out to Alex Mysinek to connect on the lending side of any transaction.
Sources
MinneapolisAssociationofRealtors.com
NAR.realtor
MortgageNewsDaily.com
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|
Social Media Links
YouTube
