Your Local Mortgage Lender
Located in Edina, Minnesota
Personalized Mortgage Experience
Alex Mysinek offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Edina, Minnesota.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
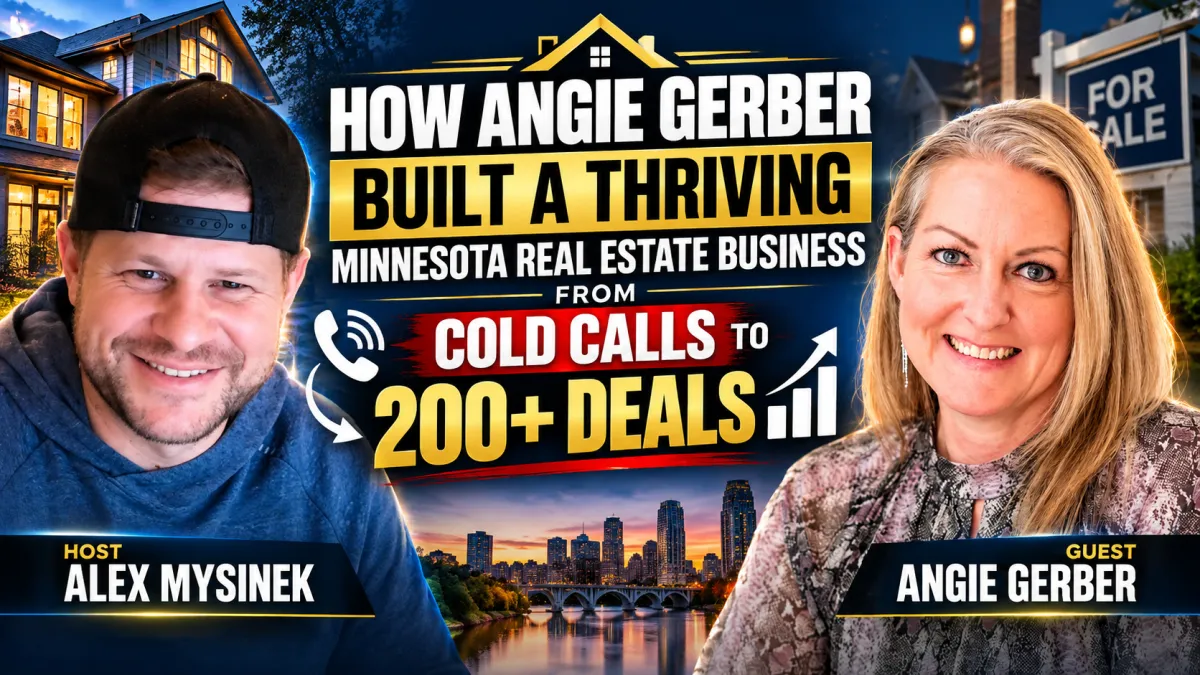
Minnesota Real Estate: Alex Mysinek Talks Market Shifts and Client Strategy With Angie Gerber of EXP
The Agent Who Left Six Weeks of Paid Vacation for a Hundred Percent Commission and Never Looked Back
Alex Mysinek sat down with Angie Gerber of EXP Realty for a conversation about building a real estate business from scratch, what the Minnesota market looks like heading into fall, and what sellers and buyers need to understand right now to make smart decisions.
Angie spent thirteen years at a company she helped grow from ten people to forty. She had a four-one-K, six weeks of paid vacation, and a clear ceiling she had hit. A friend brought her onto a real estate team with one condition. All or nothing. No part-time while you figure it out. She jumped in without a book of business, without knowing anyone in real estate, and with nothing but a servant heart and the burning knowledge that she was not going back.
She was shaking and sweating on her first cold calls. She closed over thirty deals in her first year. She now coaches and mentors other agents on how to do exactly what she did.
What She Took From Her Previous Career
Customer service, outside sales, and managing a customer service team gave Angie a foundation for working with almost any type of person and for managing herself and others simultaneously. Those skills transferred directly into real estate in ways that pure product knowledge never could. The ability to stay composed, read a client's real concern beneath what they say, and guide a conversation toward resolution is what her previous career built and what her real estate career has relied on ever since.
How She Built Her Business in Year One
She deliberately avoided her personal sphere in the beginning because she did not want to fail in front of people she knew. Instead she cold-called, worked open houses, called expireds and canceled listings, contacted for-sale-by-owners, and followed up on every buyer lead that came into the team's CRM.
The lesson she carries into coaching is about consistency and commitment. Most agents try something for a few weeks and pivot when it does not immediately produce results. Angie gave every activity long enough to actually work rather than abandoning it for the next shiny thing. She also had no option to go back which she credits as the real driver. When retreat is not on the table the path forward gets clearer.
She is now coaching and mentoring hundreds of agents and says she has met fewer than five who actually run their CRM at a high level. The agents who do are the ones who build sustainable businesses. The ones who do not are always starting over.
Where Her Business Comes From Now
Over two hundred transactions in means most of her new business comes from past clients and referrals. The work she put in during the early years built a database that now largely runs itself through the CRM when she stays consistent about staying in front of people.
Her philosophy is direct. If someone else's sign goes up in a past client's yard that is one hundred percent on her for not being top of mind. She does not blame the client for forgetting her. She takes responsibility for not showing up consistently enough to be the first name they thought of.
She keeps herself in front of her database through automated market updates, monthly property value reports, CRM-driven anniversary reminders, and handwritten cards. She sends three to five handwritten cards per day. By the end of a year the cumulative effect of that simple habit is significant in a world where almost no one sends cards anymore.
Her Santa event at the end of the year is the kind of thing clients actually look forward to. She points out that any in-person event done correctly can generate seven to ten touches when you account for the save the date, the invite, the reminders, the follow-up during the event, and the thank you afterward. Events are not just about the people who show up. They are about all the contacts that the invitation process creates.
The most powerful outreach she does is the unplanned kind. When someone pops into her mind she texts or calls immediately without an agenda. I drove past the pink house and thought of you. I saw Johnny scored the winning goal. That kind of genuine personal contact lands differently than any automated message because it is not timed by a CRM. It is prompted by a genuine moment.
Alex reinforced this from the lending side. Reaching out when something genuinely reminded you of a client is more impactful than birthday calls and home anniversary messages because everyone does those. An unexpected genuine check-in stands out precisely because it was not scheduled.
What the Minnesota Market Looks Like Right Now
Inventory is up. Price reductions are happening. The shift started showing up clearly around mid-July and agents who had eight listings were seeing five of them with no showings. Angie had a townhome sit for over three months even when it was priced correctly.
For buyers this is a genuinely good moment. Compared to two or three years ago when buyers were writing five to nine offers and losing to cash buyers at fifty to a hundred thousand over asking the current market offers something valuable. More homes to choose from. More seller flexibility on price, closing costs, and concessions. The ability to have an inspection contingency. The ability to not be in a room of twenty competing buyers.
Alex makes the point that a buyer who pays a fair price at today's rate and refinances later is in a better position than someone who paid a hundred thousand over asking at a lower rate and is potentially underwater. Affordability is about total cost not just rate. The current market rewards buyers who understand that math.
For sellers the harder conversation is about pricing expectations that are still anchored to the market of two or three years ago. Angie does not tell sellers what their house is worth. She shows them the comparables and says she interprets the market rather than making it. Buyers drive the market and the data shows what buyers are willing to pay right now. If a seller wants more than the market supports the conversation shifts to what improvements could close that gap.
The first improvements she always points to are carpet and paint because buyers dramatically overestimate what those upgrades cost. A buyer who sees carpet that needs replacing immediately thinks fifteen to twenty thousand dollars. The actual cost might be five. Replacing carpet before listing removes that mental deduction from every buyer who walks through. Paint and neutralizing the interior come next. Then kitchens and bathrooms. Those are the categories that move the needle and produce the highest return on improvement investment before listing.
Staging is presented with data not opinion. She brings the stats that show staged homes sell faster and at higher prices. If a seller declines to stage she makes the trade-off explicit. You are choosing to wait longer and likely accept less. If they are comfortable with that outcome it is their choice. If they are not the staging conversation resolves itself.
What Sellers Interviewing Multiple Agents Need to Hear
When Angie walks into a listing appointment where two or three other agents have already come through her opening question is not about price or marketing. It is why have you not signed with any of them yet. What is the underlying thing that has not been addressed?
She structures the entire conversation as mutual. They are interviewing her and she is interviewing them. She closes with the framing that one of three things will happen. They hire her today. They decide not to. Or she decides not to take the listing. That third option always gets attention because sellers are not accustomed to the possibility that an agent might pass. It resets the dynamic and creates a more honest conversation about expectations and fit.
What She Needs From a Lending Partner
Communication is the top quality. Things go sideways in transactions. What separates good lenders from average ones is not whether problems appear but how they are handled when they do. She describes her favorite lenders as solution-based and unwilling to accept no as a final answer. They exhaust every option before concluding something cannot be done and they communicate throughout the process rather than going silent when things get complicated.
Alex raised the proactive lender introduction and Angie confirmed it stands out dramatically from the norm. When a lender reaches out to the listing agent before being contacted to confirm the buyer is fully pre-approved with assets verified and AUS run that proactive communication signals a level of thoroughness that ninety percent of lenders simply do not demonstrate. In a competing offer situation that signal can tip the conversation in the buyer's favor when offers are otherwise comparable.
How to Reach Angie Gerber
Email [email protected] or reach her through [email protected]. She works with buyers and sellers throughout Minnesota.
Alex Mysinek works with buyers across Minnesota on conventional financing, investment property loans, DSCR products, and creative solutions for borrowers with complex income profiles. Reach out to Alex Mysinek to connect on the lending side of any transaction.
Sources
MinneapolisAssociationofRealtors.com
NAR.realtor
MortgageNewsDaily.com
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|
Social Media Links
YouTube
