Your Local Mortgage Lender
Located in Edina, Minnesota
Personalized Mortgage Experience
Alex Mysinek offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Edina, Minnesota.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
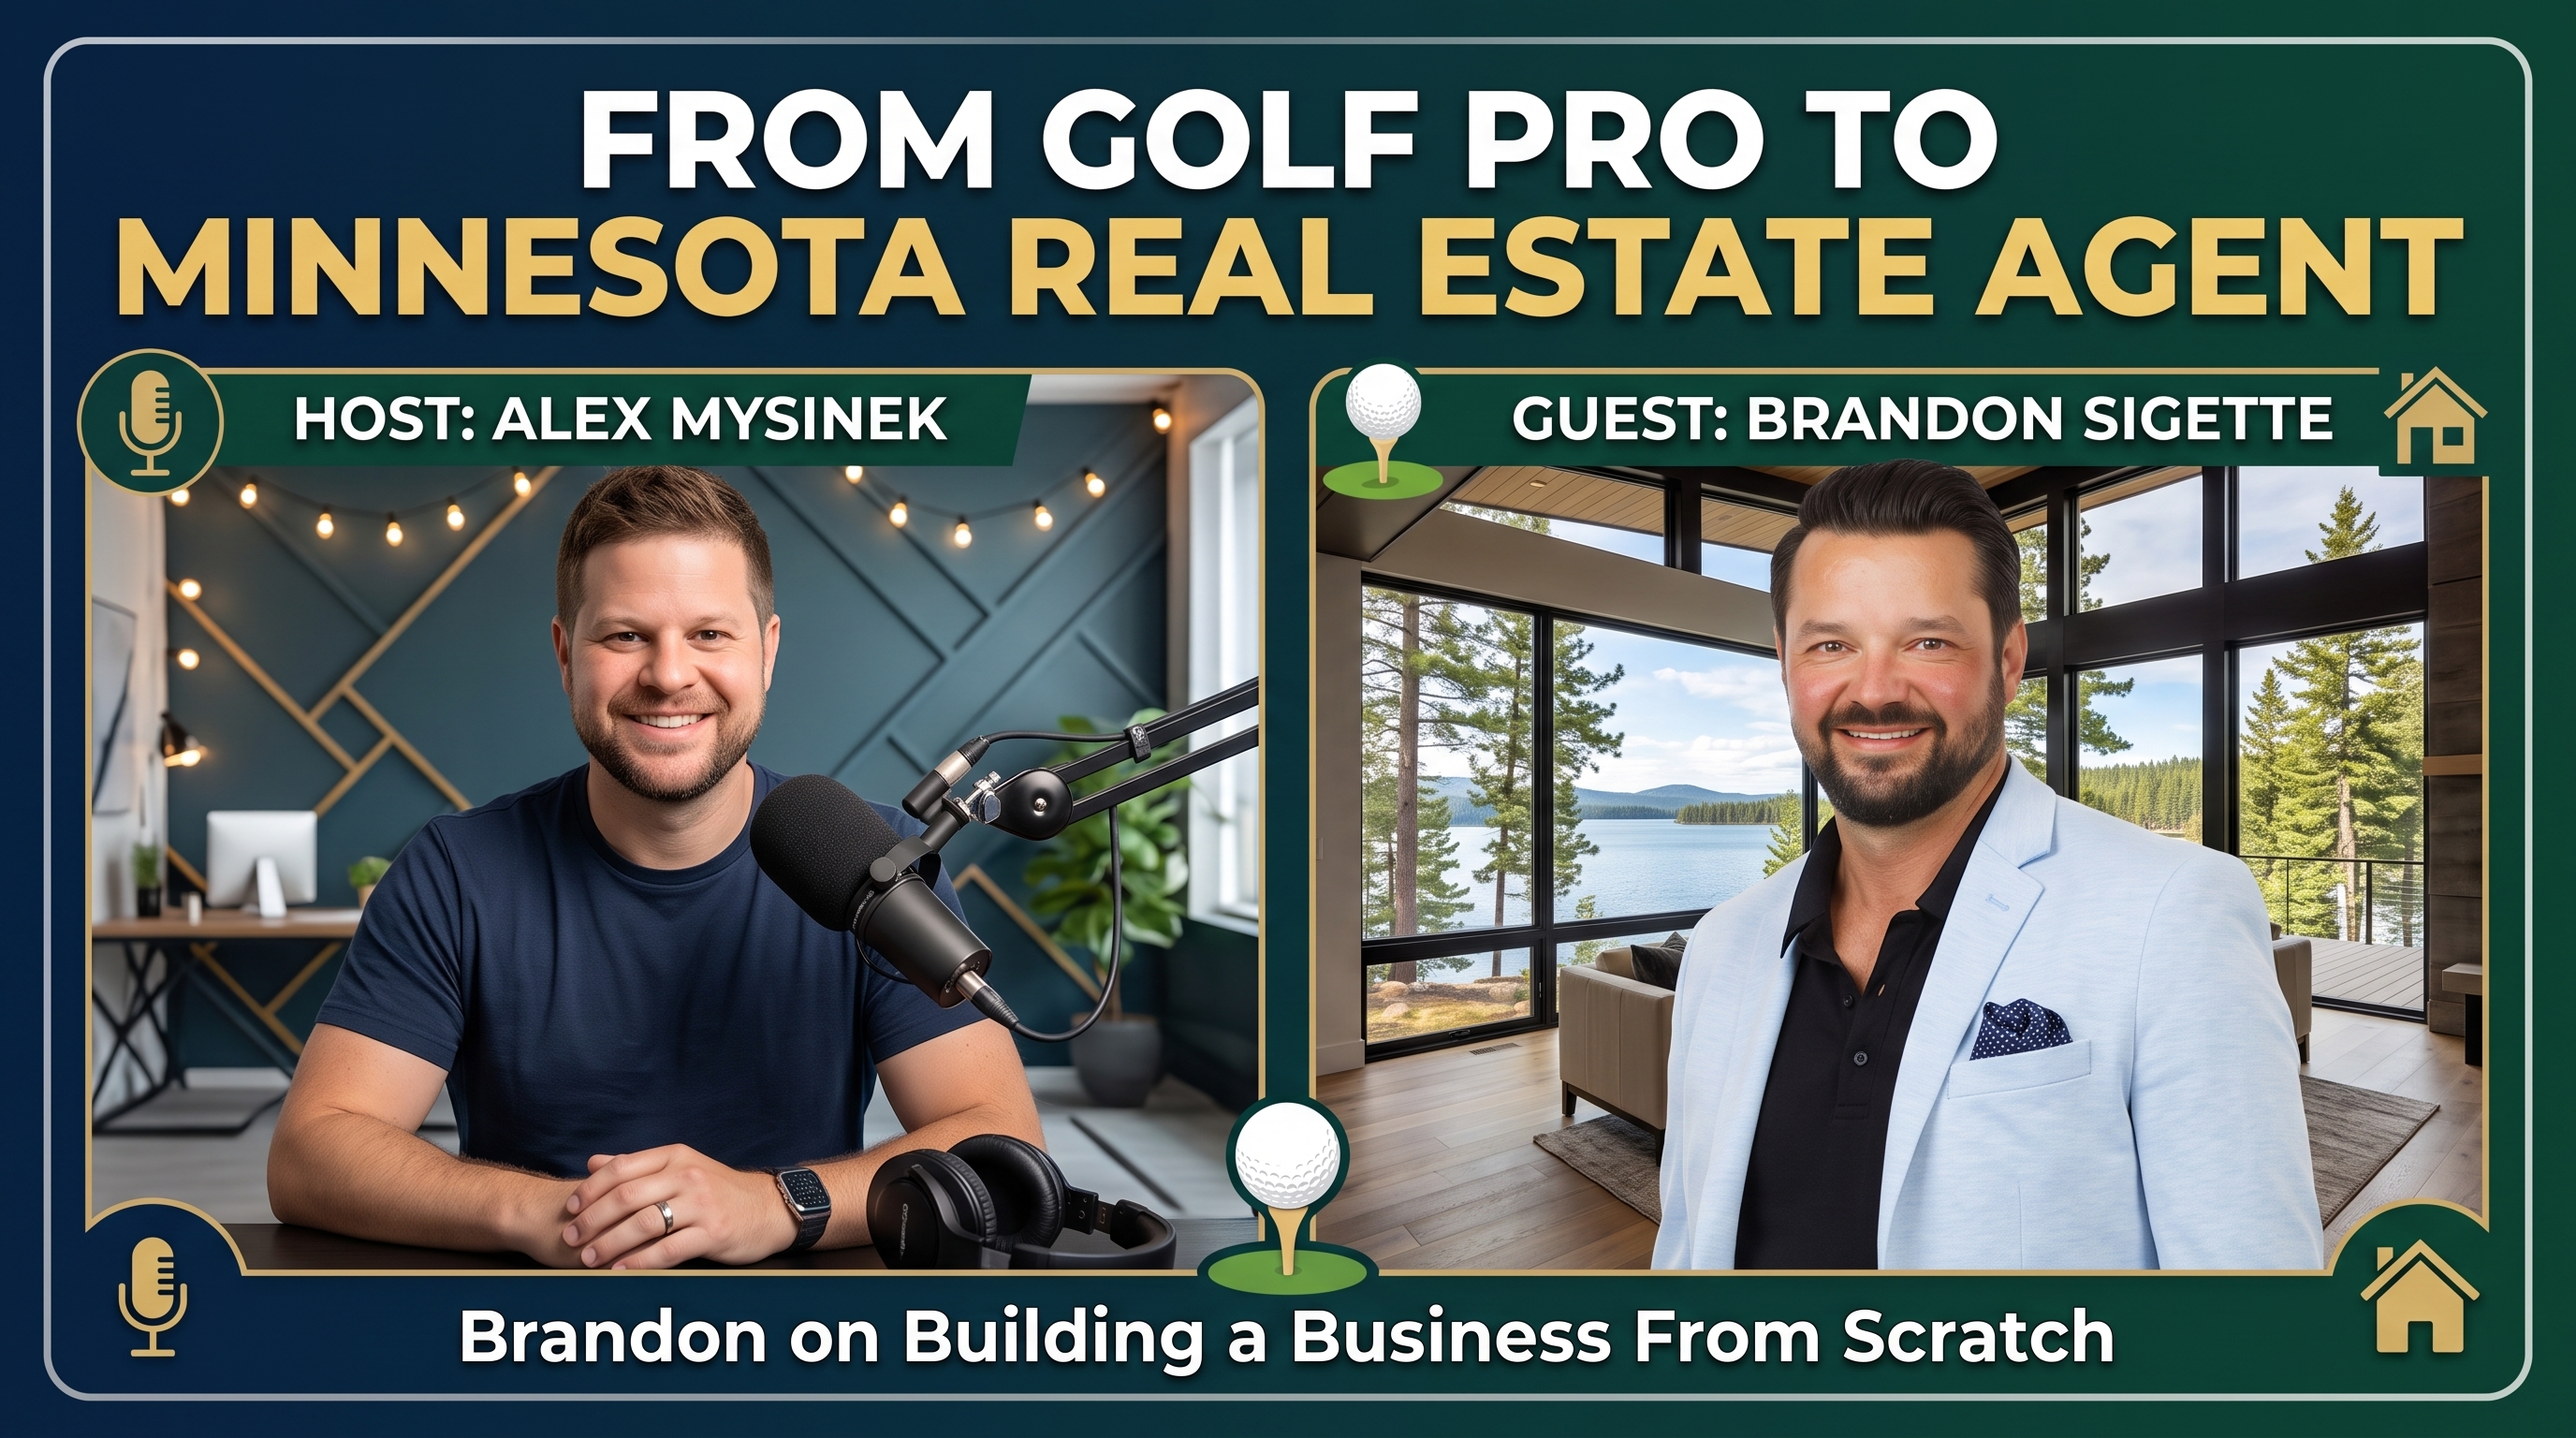
Golf Pro Turned Minnesota Realtor: Alex Mysinek Talks Market Strategy and Buyer Mistakes With Brandon
SEO Title
Golf Pro Turned Minnesota Realtor: Alex Mysinek Talks Market Strategy and Buyer Mistakes With Brandon
Meta Description
The Career Change That Happened in a Milwaukee Hotel Room
Alex Mysinek sat down with Brandon, a real estate agent in Minnesota who also runs a golf instruction business, for a conversation about what it actually takes to build a real estate career from scratch, what buyers are getting wrong in the current market, and what the Minnesota market looks like as it transitions out of summer and into fall.
Brandon's path into real estate is one of those stories that sounds spontaneous but made complete sense in retrospect. He spent fifteen years as a golf pro and five or six years as a sales rep covering a six-state territory selling clothing to golf courses and retailers. He was good at it. He was also getting burned out on the windshield time and the hotel conventions and the endless travel through Iowa and Wisconsin.
His sister and brother-in-law are custom builders in Fargo and he had always found real estate conversations with them genuinely interesting. At a sales convention in Milwaukee something clicked. He pulled out his phone and registered for his real estate classes online while sitting in that hotel room. Then he left the convention early. He had his license in three weeks and never looked back.
He reached out to one of the realtors he had gotten to know while teaching them golf. That agent pointed him toward the right brokerage and he hit the ground running with a marketing background, a built-in sphere from sixteen years of golf instruction, and a mentor who had been doing real estate for twenty-four years.
How He Built His Business in the First Year
Brandon gives significant credit to his mentor Darren Birkness who has been in the business his entire adult career and has seen essentially every transaction situation that exists. What Darren gave him was not just knowledge but a toolkit, a way of thinking about transactions and clients that saved Brandon years of learning things the hard way.
His advice for newer agents on building business is to find a mentor first and then figure out which prospecting activities match your actual personality rather than trying to copy what works for someone else. Cold calling might work beautifully for one agent. Social media might be the engine for another. Working a sphere might be the highest-return activity for a third. The key is finding the approach that feels organic rather than forced because forced prospecting comes across as sales pressure and people can feel the difference.
For Brandon the golf background gave him a natural niche. He knows what the vibe is at every club in the area. If a buyer is looking at a home on a country club Brandon can tell them things about that community that no amount of MLS research would surface. He leaned into that overlap between his two worlds rather than treating them as separate and it produced clients who felt like they were working with someone who genuinely understood what they were looking for.
What Buyers Are Getting Wrong Right Now
The biggest mistake Brandon is seeing in the current market is buyers who panic unnecessarily when they see any activity around a property. The Minnesota market has been shifting and homes are sitting longer than they were in 2020 and 2021. But when a property gets some attention buyers sometimes revert to the peak-market mentality and start thinking they have to make an offer in five minutes at twenty thousand over asking to have any chance.
Brandon's approach is direct. Put your best foot forward at a price that makes sense and is comfortable. If you do not get the house it probably was not meant to be. He has seen more than a few situations where a buyer missed a property they wanted and then found out afterward that it had serious problems they would have inherited. And then the next house came along and turned out to be the right one all along.
Sitting Down With Buyers Before the Search Starts
Brandon's first-appointment goal with every buyer is building a complete profile of what they actually need versus what they think they want. The must-haves, the nice-to-haves, the things that are negotiable, and the things that are non-starters. Once he has that picture dialed in he can look at a listing the moment it hits and know immediately whether it is worth flagging for his client.
He noted that buyers get the automated MLS portal emails just like everyone else and a property he eventually highlights for them might already be sitting in their inbox buried under thirty other listings. What he brings is the filter, the professional eye that looks at all of it and surfaces the one worth their time and attention rather than letting them drink from the fire hose and try to sort it themselves.
The education component is also consistent across every transaction regardless of how many times a client has bought. Something is always different. A new market condition, a construction vintage with specific characteristics, an inspection consideration that applies to this property but not others. Brandon does not present that education as a demonstration of being the smartest person in the room. He acknowledges that some clients know more about a specific type of home than he does and he learns from them while contributing what he knows about the deal structure and how to get the property under contract if it is the right one.
The Minnesota Market Heading Into Fall
Brandon's read on the current Minnesota market reflects a real tension between what sellers are hearing and what is actually happening on the ground. Sellers are being told the scales are tipping toward buyers and some are getting nervous about whether they will achieve what they had hoped for their home. At the same time there are still pockets of genuine buyer competition that would not look out of place two years ago.
His pitch to sellers in this environment is not that the market is fine and nothing has changed. It is that there is still a strategy that can produce above-average results if the pricing is right and the marketing is done properly. An overpriced listing that sits for sixty or ninety days is not something sellers can undo. A well-priced and well-marketed listing that comes out strong has a real chance of beating the market average even in a softer environment.
He also raised a specific tactic worth noting for listing agents with properties that have been sitting. Rather than pushing sellers toward a price reduction consider offering a seller-paid closing cost credit instead. Alex reinforced this from the lending side. Ten to fifteen thousand dollars in seller contributions can be used to buy down the buyer's interest rate, cover closing costs, and leave the buyer with more cash in the bank for furniture and initial home expenses. That outcome serves buyers who are qualified everywhere but tight on liquidity far better than an equivalent price reduction would.
What Brandon Needs From a Lending Partner
Communication. That is the consistent answer and Brandon is specific about what it looks like in practice. The best lender relationships are the ones where he does not have to chase updates because updates are already coming. Not necessarily responses required, just status notifications that keep everyone on the same page. Appraisal ordered, appraisal due, conditional approval received, clear to close. Those touchpoints provide peace of mind for the buyer and for Brandon without requiring him to become a project manager for the loan.
Alex described his own approach which includes an initial consultation focused on getting to know the borrower rather than numbers, a final lock consultation that walks through everything in detail and previews the next thirty days, and weekly update calls to everyone in the transaction. The automated emails from the company handle the status notifications and the calls handle the human relationship layer. When a file has obstacles he does not go silent. He calls and says they are working through some things and will get there. The uncertainty of not hearing anything is usually worse than knowing that someone is actively solving a problem.
Whistling Straits and Winsong Farm
The golf conversation was genuine and illuminating. Brandon grew up in a small town in North Dakota slapping it around in a field and somehow got good. He caddied for a PGA professional after college and went straight into teaching without going through the traditional assistant pro route. He has been teaching for sixteen years.
His favorite golf course in the world used to be the Makai course in Princeville, Hawaii where his sister got married. Then he played Whistling Straits and that moved to the top. Eleven hundred bunkers, no cell service, nothing but pure golf. He was hitting the driver well that day and came away with what he described as the coolest experience he has had on a course.
In Minnesota his favorite is Winsong Farm, a Tom Lehman-designed private club in the Medina-Independence area. Links style, rolling hills, multiple ways to play every hole. When the course is baked out in dry conditions a drive can trundle three hundred and fifty yards down the fairway leaving a wedge into a green that rewards creative shot-making. He recommended it without hesitation.
How to Reach Brandon
Find Brandon on Instagram at Siggy Sells MN or reach out by call, text, or email. Contact information is in the description below.
Alex Mysinek works with buyers across Minnesota on conventional financing, investment property loans, DSCR products, and creative solutions for borrowers with complex income profiles. Reach out to Alex Mysinek to connect on the lending side of any transaction.
Sources
MinneapolisAssociationofRealtors.com
NAR.realtor
MortgageNewsDaily.com
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

Social Media Links
YouTube
