Your Local Mortgage Lender
Located in Edina, Minnesota
Personalized Mortgage Experience
Alex Mysinek offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Edina, Minnesota.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
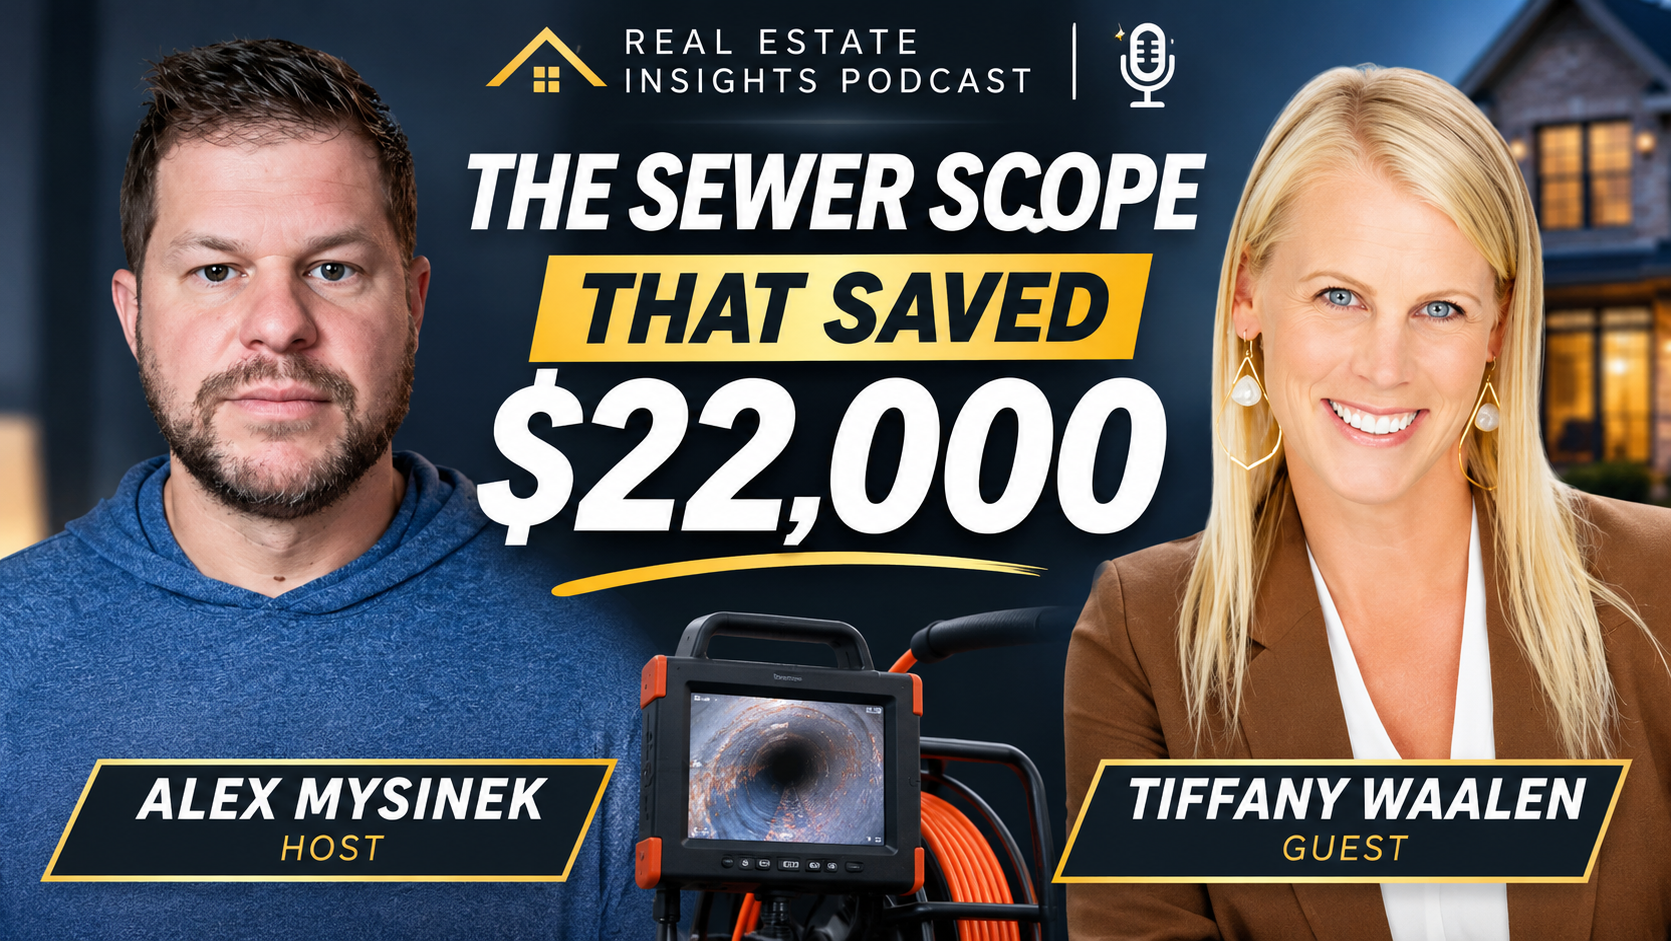
Alex Mysinek Talks Sewer Scopes, Builder’s Eye Inspections and Balancing Four Kids With Realtor Tiffany Waalen
A Realtor Who Sees Homes From Two Angles
Alex Mysinek welcomed Tiffany Waalen to the podcast to talk about what it takes to serve buyers and sellers in the North Metro while raising a young family. Tiffany is a full-time realtor, a mom of four girls all under six and a half, and she has an advantage most agents do not: her husband has been a home builder for twenty years. He is able to join her on site visits and new build walkthroughs and offer another perspective that helps protect her clients’ interests.
From Financial Services to Real Estate
Tiffany has been a full-time realtor for almost two years and in the business for about three. Before that, she spent roughly fifteen years in financial services at a large firm, working in everything from sales to project management. She lives in Andover and has resided in the North Metro all her life, but she serves buyers and sellers across the Twin Cities, from Andover to Minnetonka, Eden Prairie, and beyond. She says her earlier career, and even her years waiting tables through college and graduate school, taught her to serve people and juggle many tasks at once.
The Sewer Scope That Saved Buyers Thousands
When Alex asked about a deal where her perspective made the difference, Tiffany shared a recent story. She always encourages buyers to get an inspection, and for most homes she also requests a sewer scope, since sewer problems can hide even in newer homes and are usually costly, often in the three to five thousand dollar range. Her buyers were purchasing an older home in St. Paul, and the scope found a crack in the sewer line. The sellers agreed to fix it, which was expected to cost about $3,500. But when contractors began the repair, the entire sewer line collapsed, and the bill grew to more than $22,000. Had the buyers skipped the scope, that expense would have landed on them after closing. The scope cost only a few hundred dollars. Tiffany notes that older homes are especially prone to sewer issues, so a scope is well worth it. Alex shared that he has dealt with roots in his own sewer line, and that quick fixes do not always hold.
Looking Past the Cosmetics
Tiffany says her background with a custom builder’s family helps her look beyond the surface. Buyers, especially first-timers, can be drawn to a beautiful backsplash, redone bathrooms, or new flooring, but she looks at the bones of the house. She checks for stains on ceilings, reviews disclosures, looks for foundation cracks, and examines the grade and gutters. She is clear that she is not an inspector, which is why she always recommends a professional inspection. Cosmetic items are often easy fixes, while structural problems are not. Her goal is for her husband to join her full time within the next few years. Alex adds that catching issues early can save clients from paying for inspections on multiple homes before finding the right one.
Running a Business With Four Girls Under Six and a Half
Tiffany says being proactive is the key. She keeps a weekly to-do list and a hot list, stays in touch with clients, and plans ahead so that, for example, clients can see a new listing the day it hits the market. She works early while the house is quiet, has sought out nanny help during the week, and is not shy about asking for it. For organization, she uses her brokerage’s CRM but also keeps her own Excel spreadsheets for contacts, leads, sales, and events. Her tip for agents is to keep your own copy of your data so you never lose it if you change brokerages. Alex, a former chef, shared that the systems from his culinary career carried over well into mortgage.
Family Time and What She Hopes Her Girls Learn
On weekends, the family reserves Sundays for church and a family dinner, visits his family’s cabin up north, and enjoys the backyard, swing sets, walks, and crafts, with snowmobiling in the winter. The girls love hanging sold signs. Tiffany hopes her daughters see that they can do anything they set their minds to, run a business, and have a family at the same time. She tries to be intentional about not being on her phone and sets boundaries with clients, such as when she is putting the kids to bed. Alex agrees that being present as a parent while serving clients is one of the hardest parts of the job.
Advice for Minnesota Buyers This Season
Tiffany’s advice for families buying right now is to look within your means. Connect with a lender you know and trust, get pre-approved, and understand what payment is comfortable, including room for priorities like family trips. Alex stressed doing this early. He often gets calls on a Saturday night for offers due the next day, only to find a buyer is approved for less than the offer they want to write. Pre-approval and scenario planning ahead of time make buyers more competitive. Program rules and approval amounts vary by borrower.
Maui, Dogs and Travel Tips
Tiffany’s family loves Maui, where they own a timeshare and enjoy simple beach days and whale watching. She has plenty of tips for traveling with a large family. They also have two Westies at home, while Alex has a Great Dane and a French bulldog.
How to Reach Tiffany Waalen
Anyone looking to buy or sell in the North Metro and Minnesota suburbs, including new construction, can find Tiffany on Facebook and Instagram, where she is active. Her contact links and email are in the show notes.
Alex Mysinek helps Minnesota buyers with mortgage financing and encourages you to get pre-approved early so you can move with confidence. Reach out to Alex to start planning your next purchase.
Sources
NAR.realtor
ASHI.org
ConsumerFinancialProtectionBureau.gov
Realtor.com
HUD.gov

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|
Social Media Links
YouTube
