Your Local Mortgage Lender
Located in Edina, Minnesota
Personalized Mortgage Experience
Alex Mysinek offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Edina, Minnesota.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
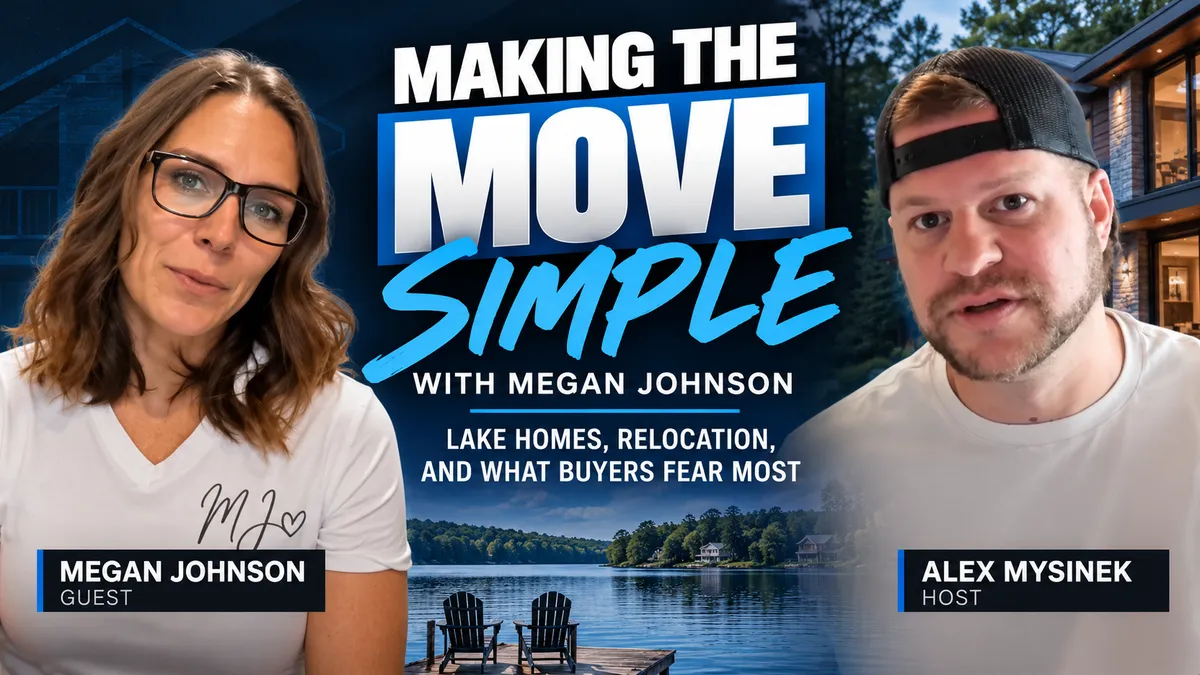
Alex Mysinek Talks Making Moves Simple Lake Homes and Relocation Buyers With EXP’s Megan Johnson
The Franchise Manager Who Said I Need a Little More and Built a Real Estate Business Around Simplicity
Alex Mysinek sat down with Megan Johnson of EXP Realty for a conversation about what six years of helping buyers, sellers, and investors across Minnesota has taught her, why communication during a chaotic transaction matters more than a smooth one, what lake home buyers consistently underestimate, and what she actually wants from a lending partner beyond the things everyone already says they want.
Megan spent years managing companies in the McDonald’s and Massage Envy systems before coming home one day and telling her husband she needed more. His response was characteristically direct. Just do it. That simplicity, his willingness to make a complex decision feel manageable, became the foundation of her real estate philosophy and her brand name. Making Move Simple was not a marketing exercise. It was a description of who she already was before she knew she was going to need it professionally.
Why She Was Drawn to Real Estate
Before getting her license Megan and her husband bought a home and went through several agents before finding one that genuinely clicked. That experience taught her two things. How important the right agent relationship is for a buyer going through one of the most significant transitions of their life. And how much the wrong fit can cost people in stress, confusion, and missed opportunities.
She and her husband moved an hour from where they had been living. They changed their favorite gas station, their commute, how often they saw family. The accumulated weight of those changes on top of the transaction itself is something most buyers do not fully appreciate going in. Megan felt it personally and it became the lens she uses with every client she works with.
What Buyers Are Actually Afraid of Right Now
The rate conversation comes up constantly in Megan’s business and her read on it is more nuanced than most. When a buyer says they are waiting for rates to drop there is almost always more behind that statement than rates. The buyers who are genuinely ready to purchase understand that rates will flex over time and their attention has already moved to what ownership actually costs. Furnaces. Air conditioning units. Roofs. Concrete. The big ticket items that transfer from seller to buyer at closing and become the new owner’s financial responsibility in the years ahead.
The buyers focused on rates are often buyers who are not quite ready for reasons that have nothing to do with the interest rate environment. Megan works with what is actually going on rather than the surface explanation because that is where the conversation that actually helps someone starts.
The Step-by-Step Approach That Makes the Process Feel Less Overwhelming
Megan’s first conversation with any buyer starts with where they want to be in five years. That forward-looking question tells her more about the right path through the purchase than any checklist of bedrooms and square footage could provide. From there the process is about setting expectations clearly and consistently so nothing in the transaction arrives as a genuine surprise.
She tells every client upfront that something unexpected will come up. There will be something she has never seen before. But they will go through each step together and get through it. That advance framing changes how clients respond when something difficult happens because they were told it was coming in some form rather than encountering it cold.
The transactions she is most proud of are not the smooth ones. They are the chaotic ones where the communication was so consistent and the expectation-setting so thorough that clients left five-star reviews about a process that was objectively a mess from the inside. That outcome is only possible when clients feel someone is genuinely in their corner throughout.
What Lake Home and Cabin Buyers Consistently Underestimate
The variety within the lake property category surprises almost every buyer who enters it for the first time. When someone says they want a lake home in Minnesota the follow-up questions that actually matter are far more specific than most buyers anticipate.
What kind of lake? A recreational lake with heavy boat traffic on summer weekends is a fundamentally different experience from a quiet wildlife lake with no-wake rules. What county? What type of shoreline access? A gradual slope to the water is a different property from one that sits high on a ridge with stairs or a funicular required to reach the lake. Megan has seen buyers arrive at a showing to discover two hundred stairs between the cabin and the dock without having considered whether that was acceptable to them before driving two hours to look.
The size variation within the category also surprises buyers. Two-bedroom, one-bath cabins in Minnesota can range from six hundred square feet to fifteen hundred. Thirty feet of shoreline is a different property from a hundred and fifty feet regardless of what the listing price says. Some buyers care most about the cabin itself and are willing to accept a smaller or less accessible lot. Others care entirely about the shoreline and the outdoor experience and will accept almost any cabin if the water access is right. Understanding which type of buyer is in front of her before the showings begin saves everyone significant time.
How She Works With Relocation Buyers
Out-of-state buyers coming to Minnesota require more conversation upfront and Megan gives it to them without rushing toward the search. The first questions are about why Minnesota and what they expect from being here. Have they visited? Have they researched the specific area they are considering?
The biggest risk for a relocating buyer is ending up in a community that does not fit their life in ways they could not have known without some research. Loving the house but struggling with the location six months in is a situation Megan works actively to prevent by ensuring buyers understand the area before they commit to a specific property. That means sometimes slowing down the search conversation to focus on the community, the commute, the feel of different neighborhoods, the things that will determine whether someone is happy in the location rather than just in the home.
What She Actually Wants From a Lending Partner
Alex tries to get Megan off the communication answer by telling her she cannot say it. Her response reframes the question in a way that is genuinely more specific and useful. What she is looking for beyond communication is the ability to adapt how loan programs and options are explained to each individual client.
Buyers nod along in conversations they do not fully understand. They say yes without genuinely absorbing what they agreed to. A lender who explains things the same way to every borrower is going to leave a meaningful percentage of clients confused even if those clients never say so. What Megan values is a lending partner who can read the client, shift the explanation, find the analogy or the framing that lands for that specific person, and make sure the yes at the end of the conversation reflects genuine understanding rather than polite agreement.
She puts it simply. She wants to make sure clients understand what they are saying yes to. Anything less than that is not serving the client regardless of how efficient the transaction feels on the surface.
How to Reach Megan Johnson
Find Megan on Facebook at mj.makemovessimple and on Instagram and YouTube under the same handle. She works with buyers, sellers, and investors from the Twin Cities across Minnesota including lake country and cabin properties throughout the state.
Alex Mysinek handles mortgage financing for buyers throughout Minnesota and is available for pre-approval conversations, loan structure analysis, and the kind of flexible client-specific explanation that Megan just described as her most important requirement in a lending partner. Reach out to Alex to connect on the lending side of any Minnesota transaction.
Sources
MinneapolisAssociationofRealtors.com
NAR.realtor
MortgageNewsDaily.com
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

Social Media Links
YouTube
