Your Local Mortgage Lender
Located in Edina, Minnesota
Personalized Mortgage Experience
Alex Mysinek offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Edina, Minnesota.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
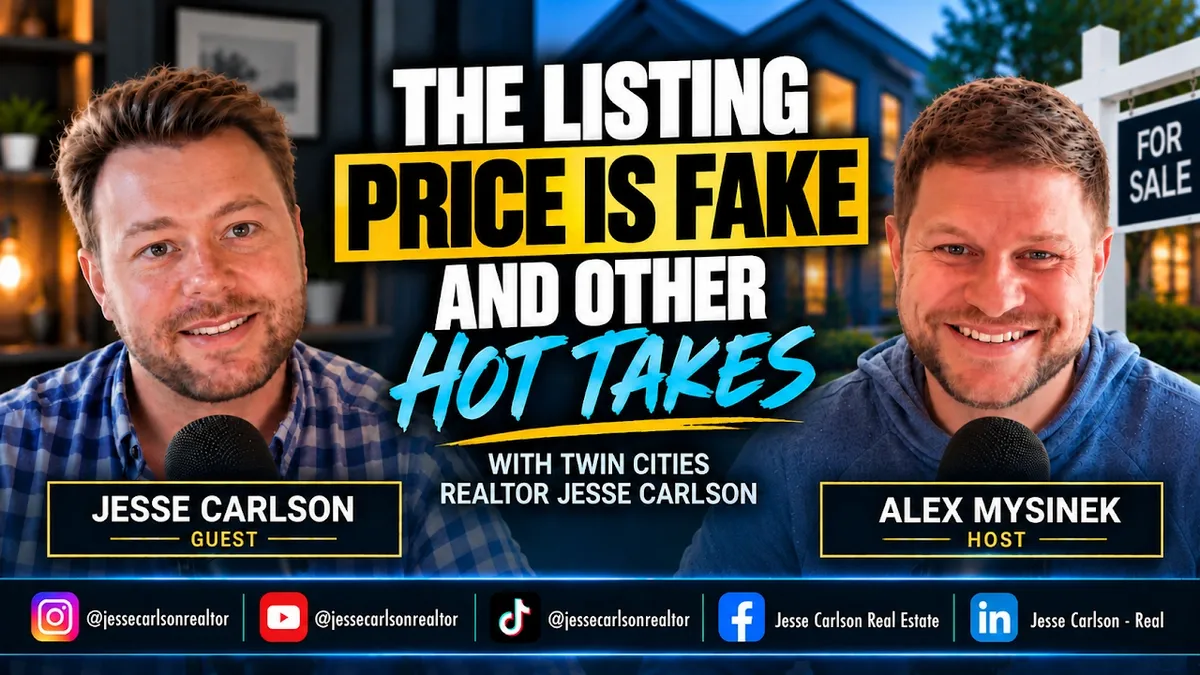
Alex Mysinek Talks Listing Price Hot Takes Restaurant Industry Roots and Buying Strategy With Jesse Carlson
Two Restaurant Industry Veterans With Unconventional Takes on Real Estate
Alex Mysinek sat down with Jesse Carlson of Real Broker in the Twin Cities for a conversation that immediately abandoned the standard origin story format in favor of something more honest, more practical, and considerably more fun. Jesse studied political science, psychology, and theater before spending seven years in restaurants and then pivoting to real estate during the pandemic. Alex spent twelve to thirteen years as a chef including time at Nordstrom, Jake City Grills, Hazelwood Grill and Tap Room, and eventually hospital nutrition operations before moving into mortgage lending. Both of them arrived at the same conclusion independently. The restaurant industry is significantly harder than anything real estate has thrown at them since.
The conversation covers hot takes on listing prices and appraisals, how hospitality skills translate directly to client work, what Jesse actually watches for when showing homes, how to handle couples with completely different priorities, and a genuinely interesting prediction about the future of shared investment properties up north.
The Listing Price Hot Take
Jesse’s opening hot take is direct. The listing price is fake. He is careful to clarify what he means before anyone takes that too literally. The listing price is real in the sense that it is posted, it is visible, and it is tangible. What it is not is the price the home is likely to sell for.
He ran the numbers over the previous ninety days across the Twin Cities market. Approximately thirty percent of homes sold above list price. Approximately forty to fifty percent sold below. Only about twenty percent transacted within the listing price band. That means roughly eighty percent of buyers looking at a listed price and treating it as the number the home will sell for are working with a figure that will likely be wrong in one direction or the other.
The practical takeaway for buyers is not to get locked in on the listed price as a ceiling or a floor. If a home appears to be heading toward a below-list outcome that is often a signal to move toward it rather than away from it.
Alex connects this to the appraisal side of the transaction with a point Jesse finds impossible to argue with. When a home goes under contract at ten thousand above list price the appraisal comes in at the contract price almost every time. Jesse agrees and adds that despite all the line items and comparables and adjustments that go into a formal appraisal the end result is less scientific than most people assume. There is typically a condition line or a similar subjective adjustment that gives the appraiser flexibility to land where the contract needs them to land. The home’s value at any given moment is more accurately described as a range of what an array of buyers might pay rather than a single defensible number. Jesse recently got his divorce certification and has been having exactly this conversation with divorce attorneys who need to understand the difference between a realtor’s market analysis and a formal appraisal.
How Restaurant Experience Maps Directly to Real Estate
Both Jesse and Alex find the connection between their previous careers and their current work almost perfectly symmetrical. Jesse’s framing is the most elegant. Every table that comes into a restaurant requires the same read. What is the occasion? What kind of budget are they on? Are we doing burgers and celebration or is this just an easy apps night? Reading the table and adjusting the experience accordingly while running multiple tables simultaneously is the same skill as running multiple buyer and seller consultations at different stages of the process. The check at the end of dinner is the closing table.
Alex adds a dimension to the metaphor that Jesse immediately embraces. The server is the front of house person who is visible to the client throughout the experience. The kitchen is the back of house operation that makes everything actually happen once the order is placed. In real estate terms the realtor is front of house and the lender is back of house. Same goal, same client, completely different daily experience of the work.
Jesse also uses the restaurant analogy to explain team building and business growth. The solo agent trying to do everything is the one server running the entire floor alone, busing tables, running drinks, taking orders. Adding a transaction coordinator is like adding a busser. Adding a showing assistant is like adding a drink runner. Each addition lets the agent stay in front of more clients rather than getting pulled into tasks that someone else can handle more efficiently.
What Jesse Is Actually Watching When He Shows a Home
The seven-second rule in real estate is real according to Jesse. Buyers know within roughly seven seconds of entering a home whether they are seriously interested. What he watches for is body language, posture, and how quickly the energy shifts when they walk through the door.
But the more interesting part of his approach happens before the showing. He asks buyers what they do for fun. It is a question most agents skip and he thinks it is one of the most important questions in the process.
What someone does for fun often tells you more about what they need from a home than any list of bedrooms and square footage could. Do they host board game nights? Dinner parties? Are they into theater and want space for a sing-along piano gathering? Do they need a garage that functions as a workshop? Do they want land for an ATV or a snowmobile? The layout and location requirements that come out of those answers are often completely different from what a standard buyer intake form would produce. He also asks how handy they are which tells him how much deferred maintenance or fixer-upper potential makes sense for their situation.
How to Handle Couples Who Want Completely Different Things
Jesse was recently coaching another agent on a couple with seemingly incompatible priorities. One wanted space and land. One wanted a walkable suburban neighborhood for the kids. The agent’s instinct was to find the compromise in the middle. Jesse’s advice was to not do that.
Splitting the difference on location and lifestyle priorities produces a home where neither person is fully happy. His reference point is the concept from Chris Voss’s negotiation work. Wearing one black shoe and one brown shoe is not a compromise anyone should want.
Instead he goes deeper with each person separately. He asks what is important to them about their priority, not just what the priority is. In the situation he was coaching the space-and-toys priority turned out to be about having room for recreational vehicles and outdoor equipment. The suburban-neighborhood priority was about trick-or-treating, neighborhood kids, and a specific vision of family life. Those two things are not inherently compatible in a single property but they are potentially solvable through a different structure. A slightly smaller primary residence in the right school district and neighborhood, paired with an investment property or cabin up north that provides the land and storage. Two properties serving two different sets of needs can be a better solution than one property that serves neither well.
The Hot Take About What Is Coming for Millennial Buyers
Jesse closes with a prediction that Alex finds genuinely interesting. He sees a future where groups of millennial friends begin purchasing shared investment properties together. A compound up north that a group of friends co-own, splitting usage and costs. The structure is essentially a modernized version of the timeshare concept but among trusted people rather than a resort company. As he gets deeper into commercial real estate and learns more about syndications he sees the framework already existing. The appetite for shared ownership among younger buyers who want access to space and outdoor recreation without bearing the full cost alone is real and he thinks it is going to find a form in the market over the next decade.
Alex’s vote is for a version in Colorado mountains. Both of them would sign up immediately.
What Brings Jesse to Real Estate Every Day
When Alex asks whether real estate ever feels stressful compared to restaurants Jesse’s answer is honest. It is more complex and the stakes are higher for clients. But the kind of stress is different and for both of them the comparison to what they experienced in the service industry makes real estate feel manageable by contrast. Alex describes losing sleep in his early loan officer days over income calculations and underwriting questions. He also describes the freedom of running his own schedule and business as something that never gets old when you come from a world of eighteen-hour food truck shifts and standing over hundred-and-fifty-degree stoves.
Jesse’s version is the depth of the relationship. In a restaurant you help someone have a great night. Maybe you see them again as a regular. In real estate you are helping someone make the most significant financial decision of their life and the connection that comes from doing that well is a different kind of relationship entirely. Every deal teaches something. Every couple or individual or investor comes with a different set of priorities that requires a different approach. It is genuinely interesting work and for someone who studied political science, psychology, and theater before waiting tables for seven years that variety is exactly the right fit.
How to Reach Jesse Carlson
Find Jesse on Instagram at Jesse Carlson Realtor and on Facebook as Jesse Carlson. Email jesse at jessiecarlson.com. He works with buyers, sellers, and investors across the Twin Cities at Real Broker and is getting deeper into commercial real estate and investment property conversations as well.
Alex Mysinek handles mortgage financing for buyers throughout Minnesota and is available for pre-approval conversations, loan structure analysis, and the kind of practical explanation that helps buyers understand what their options actually are before they fall in love with a home. Reach out to Alex to connect on the lending side of any Twin Cities transaction.
Sources
MinneapolisAssociationofRealtors.com
NAR.realtor
MortgageNewsDaily.com
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

Social Media Links
YouTube
