Your Local Mortgage Lender
Located in Edina, Minnesota
Personalized Mortgage Experience
Alex Mysinek offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Edina, Minnesota.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
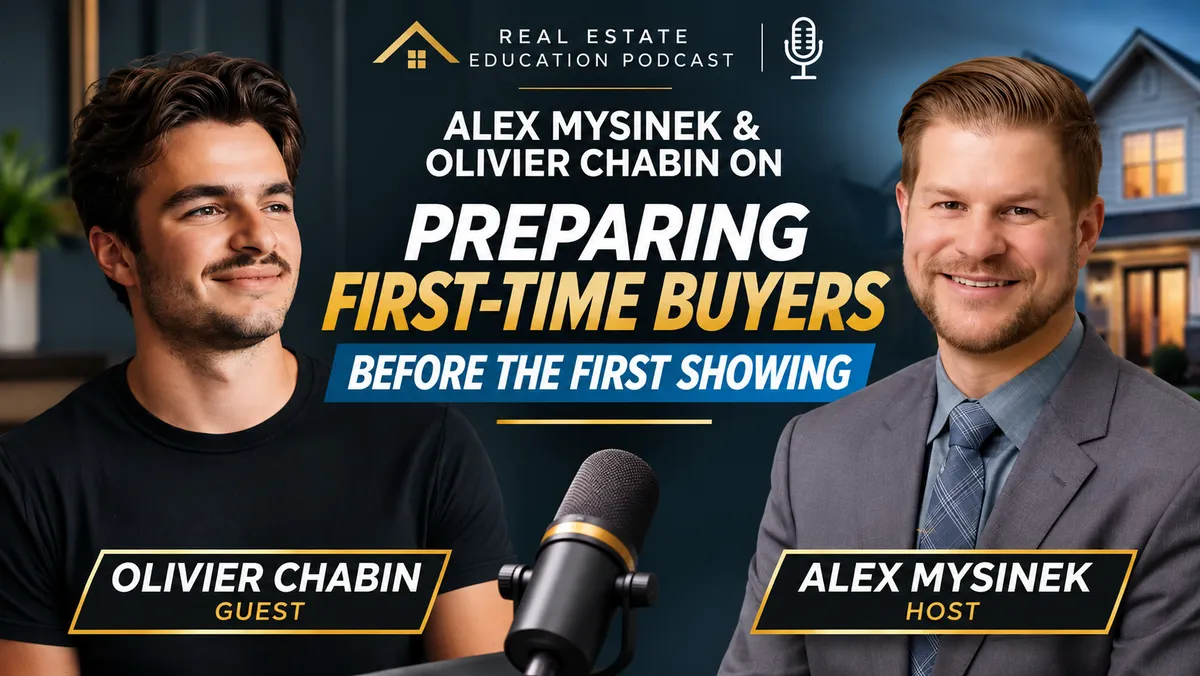
Alex Mysinek Talks First-Time Buyer Strategy and Rate Buydowns With Edina Realty’s Olivier Chabin
A Transparent, Education-First Approach to Buying
Alex Mysinek welcomed Olivier Chabin of the Sohus Real Estate Group at Edina Realty to the podcast for a conversation about guiding first-time buyers through the process in today’s market. Olivier is licensed in Minnesota and Wisconsin and is the son of first generation immigrants, a background that shapes how he helps clients through a process that can feel completely new. His game plan on every file is to be as transparent as possible, explain every step of buying or selling, respond quickly, and leave nothing hidden so clients have full information when making one of the biggest decisions of their lives.
Two Meetings Before Any Home Tours
Olivier meets with every incoming buyer twice before looking at a single property. The first is a buyer consultation, where he reviews the buyer’s goals and walks through the entire process from start to finish, including the lender and title team needed to close. Once the buyer understands the steps and has a timeline, the second meeting is what he calls a refined focus meeting, where they set search criteria such as bedrooms and location. Only then do they tour homes, where he points out items like an older furnace that represent future expenses for a first-time buyer. The goal is for both sides to be on the same page about what the buyer wants and what to expect from him.
What Buyers Are Concerned About Right Now
Olivier says he is not hearing a massive concern about the market in general. Minnesota still has lower inventory than many other states, which brings some peace of mind. Technically it remains a seller’s market by inventory, but buyers have a great deal of leverage in negotiation. His advice is that buyers may need to bite the bullet on the rate for now and refinance later, while using today’s conditions to negotiate a lower purchase price. Inventory is rising, and many buyers are waiting on the sidelines for rates to fall, which could send prices back up once they return.
Focus on the Payment, Not the Rate
Alex shares the comparison he makes for clients. Three years ago, rates were lower, but homes were selling 50 to 70 thousand dollars over asking with no inspections. Today rates are higher, but buyers can negotiate 25 to 50 thousand dollars off the price. You cannot refinance a purchase price, but you can refinance a rate if rates come down, and nobody knows when that will be. His advice is to focus on whether the payment is affordable and worry about the rate later.
Using Seller Concessions and Buydowns
Olivier says it is rare now that he cannot get either a price reduction or at least seller-paid closing costs. For many first-time buyers he recommends using seller-paid closing costs toward a rate buydown, which can bring the monthly payment back into a comfortable range. He notes that sellers who bought at the peak and are trying to break even are harder to negotiate with, while sellers who have owned for years have more flexibility. In a recent $200,000 purchase, he secured $10,000 off the price and $10,000 in seller credits, part of which went to a rate buydown.
He leaves the numbers to the lender and encourages buyers to run side-by-side scenarios, such as a lower price versus a buydown, over five, ten, and twenty years.
How Olivier’s Background Shapes His Service
Olivier says his background makes him more open to understanding where clients are coming from when processes are unfamiliar. For buyers from outside the country, he sees financial literacy as fairly universal, so his role centers on helping them understand the Minnesota market and which areas fit best. The mortgage programs themselves are something to review with a lender. Ultimately he wants every client to have a solid, simple roadmap.
What a Realtor Needs From a Lender
Olivier values communication above all, including responsiveness during the day and into the early evening when offers are being shaped. He also wants lenders who clearly explain financing, fees, and each step. He has worked with lenders who give formal presentations and those who run numbers conversationally, and finds that a presentation answers many questions up front.
How Alex Onboards Buyers
Alex explains that he typically begins with a needs and goals call of 15 to 20 minutes focused on payment, cash to close, down payment assistance, and timeline. After the application and documents, he holds a loan consultation using Mortgage Coach for number-oriented buyers or MBS Highway for a simpler view, covering every line of the estimate. He also asks buyers to send him addresses before weekend showings so he can provide estimates with rate, payment, and cash to close, helping them compare homes using real numbers. He adds that lenders paid only on closing are strongly motivated to be available nights and weekends, and that his team has a system to issue pre-approvals at odd hours.
How to Reach Olivier Chabin
Olivier is easiest to reach by phone or email, and he is also responsive on Instagram.
Alex Mysinek helps buyers across Minnesota with mortgage financing, including rate buydown strategies and first-time buyer options. Reach out to Alex to talk through your numbers before you start touring homes.
Sources
NorthstarMLS.com
MNRealtor.com
Realtor.com
FreddieMac.com
ConsumerFinancialProtectionBureau.gov

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

Social Media Links
YouTube
