Your Local Mortgage Lender
Located in Edina, Minnesota
Personalized Mortgage Experience
Alex Mysinek offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Edina, Minnesota.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
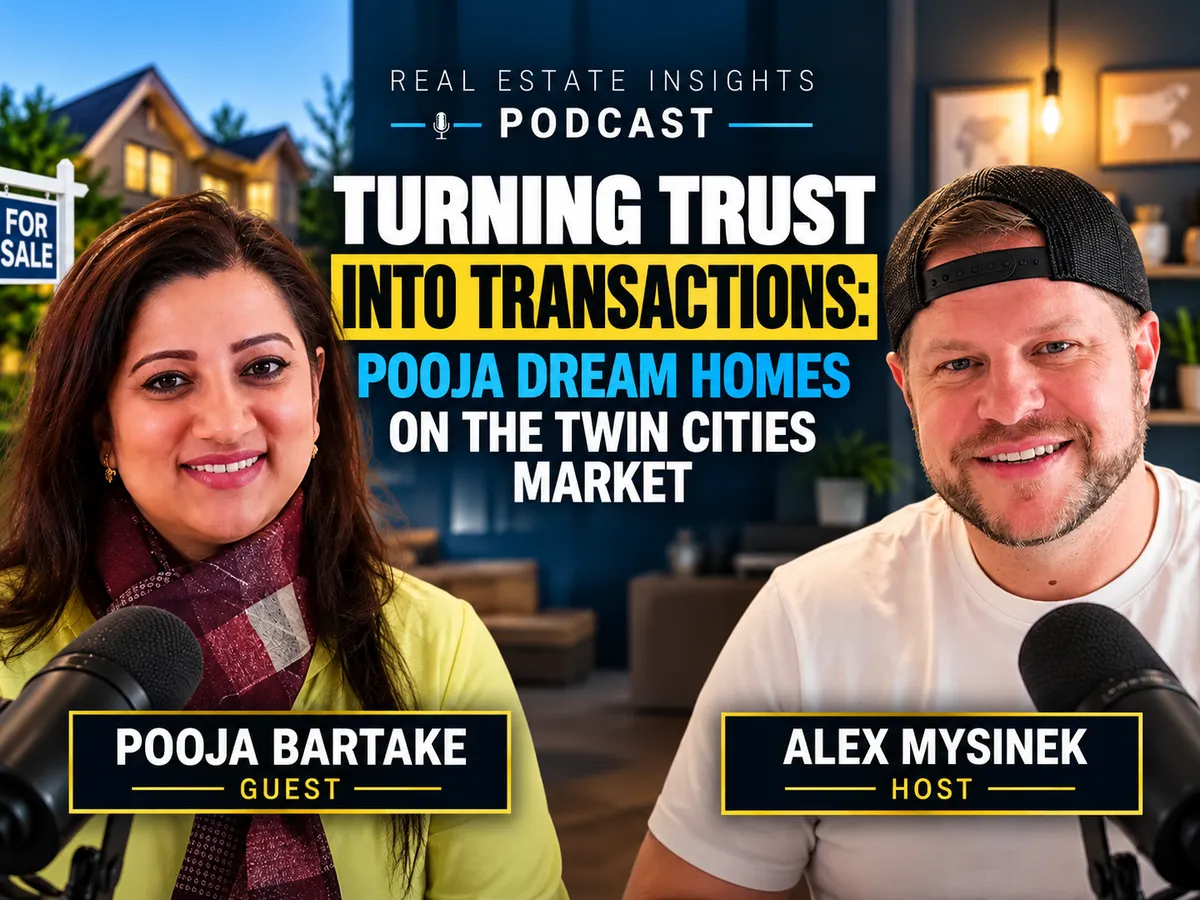
Alex Mysinek Talks First Time Buyer Misconceptions AI Tools and the Twin Cities Market With Pooja Bartake
The Textile and Payroll Professional Who Found Her Home in Real Estate
Alex Mysinek welcomed Pooja Bartake of Dream Homes to the podcast for a conversation about what three years in Twin Cities real estate has taught her, why first-time buyers are operating on misconceptions that are keeping them out of the market longer than necessary, how she stays connected with past clients without it feeling transactional, and what the current market is offering buyers who are financially ready but debating timing.
Pooja came to real estate from two seemingly unrelated backgrounds that turned out to be more relevant than she expected. Her creative side came from textiles which gave her an eye for staging and presentation and an instinct for how homes should be positioned visually. Her analytical side came from payroll and accounting work which gave her comfort with numbers and an ability to help investment clients think through returns clearly. She did not plan for either background to matter in real estate. They both do.
The personal trigger for getting into real estate was her own home buying experience. She and her husband went through the process without anyone they trusted guiding them. That feeling of navigating something significant without a reliable advisor became the motivation to become that advisor for other people.
How She Builds a Referral Business That Does Not Feel Like a Referral Business
The majority of Pooja’s business comes from referrals and she attributes that directly to how she maintains relationships after transactions close. The key is that the relationship does not feel like a professional follow-up campaign. It feels like staying in touch with people she genuinely cares about because that is what it actually is.
Her system involves touchpoints at least once a quarter through a combination of genuine outreach and useful market information. Seasonal home maintenance tips, market updates, and check-ins that are more friendly conversation than business development. The people who refer her have become part of a community she has built rather than a client database she manages. That distinction shows up in how the interactions feel and it is why those people send her their friends.
Alex asks how she keeps track of all of it and Pooja uses Follow Up Boss as her CRM. The system handles the mechanical side of staying organized so her attention can go toward the content and the relationships rather than trying to remember who she has and has not contacted.
The AI Conversation That Went Down a Delicious Rabbit Hole
Alex cannot stop talking about Grok, the AI platform from xX that recently dropped from three or four hundred dollars a month to twenty dollars, and he is using it to build automated workflows connected to his CRM and email. The version he is most excited about in the moment is a grocery automation bot he built for his wife that pulls ingredients from her weekly recipes, cross-references against what is already in the house, and automatically orders the difference from Whole Foods.
Pooja is immediately interested in this for herself and Alex promises to report back on whether it actually works given that he built it the previous Sunday. Both of them agree that AI is genuinely useful for business operations when the use case is right and that it is worth exploring thoughtfully rather than dismissing.
The Biggest Misconception Holding First-Time Buyers Back
The number one thing Pooja hears from first-time buyers is that they believe they need twenty percent down to buy a home. That single misconception is keeping people out of homeownership longer than they need to be and it is the most common starting point for her education conversations.
Once she explains the range of options available including lower down payment conventional programs, FHA financing at three and a half percent, down payment assistance programs, and various other structures the conversation shifts from I cannot to I can. That shift is the whole point of the first meeting with a first-time buyer.
Alex adds the rate buydown conversation to this and walks through why a seller-funded two-one buydown is particularly powerful for first-time buyers right now. At a seven and a half percent rate a two-one buydown puts the buyer at five and a half percent in year one and six and a half percent in year two with the seller funding the cost. If rates improve enough to refinance during that window the unused portion of the buydown can reduce the principal balance. The buyer never pays for this out of pocket when it is negotiated as a seller concession.
His honest assessment is that for a sophisticated buyer this is essentially moving money between pockets. But for a first-time buyer who needs the psychological comfort of a lower starting payment and who may not trust themselves to put the equivalent cash into investments the buydown produces a real behavioral benefit that justifies the structure.
The TBD Underwrite That Removes Anxiety From the Process
Alex describes one of the tools he uses regularly with first-time buyers that goes beyond the standard pre-approval. A TBD underwrite sends the pre-approval to an actual underwriter before a contract is in place. The underwriter fully reviews the file so that by the time the buyer is making offers the only remaining variable is the property itself. Nothing about the borrower’s qualification can surface at the last minute to threaten the transaction.
Pooja immediately recognizes the value of this not just for the buyer but for the seller. A seller receiving an offer from a buyer whose file has been fully underwritten has a significantly higher level of certainty that the deal will close. That certainty has value in a negotiation.
What the Current Market Is Telling Buyers About Timing
November and December in Minnesota are traditionally slower for real estate. Alex and Pooja both see that as an opportunity rather than a reason to wait until spring.
Sellers who are on the market during the winter months are there because they have to be. Relocation, life changes, financial motivations. Whatever the reason the seller listing in November is a motivated seller and motivated sellers negotiate differently than sellers who can afford to wait for the spring rush.
When spring arrives more buyers enter the market simultaneously and that competition reduces negotiating leverage, pushes prices higher, and makes it harder to ask for the seller concessions and closing cost contributions that are available right now. The buyer who acts in the quieter season gets the deal. The buyer who waits for spring gets the competition.
Pooja’s framing is simple. If you are financially ready there is no reason to wait. The right home at a favorable price with motivated seller negotiation is available right now. It will be harder to find and more expensive to purchase when everyone else decides the timing feels right.
Alex makes the historical comparison directly. Three years ago buyers were paying a hundred thousand over asking, making offers sight unseen, and competing against twenty other buyers on the same property. The rate was lower but the purchase price was dramatically higher and many of those buyers are now upside down on properties they overpaid for. Today’s buyer can get a home under market value with seller-paid closing costs and a rate they can refinance when conditions change. The purchase price is permanent. The rate is not.
How to Reach Pooja Bartake
Pooja Bartake is with Dream Homes serving buyers and sellers throughout Minneapolis, St. Paul, and the surrounding suburbs including first-time buyers, relocation clients, new construction, and investment properties. Reach out to Pooja directly to start the conversation about buying or selling in the Twin Cities.
Alex Mysinek handles mortgage financing for buyers throughout Minnesota including the TBD underwrite, down payment assistance programs, rate buydown strategy, and the educational conversations that help first-time buyers understand what they actually qualify for rather than what they assumed. Reach out to Alex to connect on the lending side of any Twin Cities transaction.
And if anyone has a great biryani recipe Pooja would probably appreciate the competition.
Sources
MinneapolisAssociationofRealtors.com
NAR.realtor
MortgageNewsDaily.com
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

Social Media Links
YouTube
