Your Local Mortgage Lender
Located in Edina, Minnesota
Personalized Mortgage Experience
Alex Mysinek offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Edina, Minnesota.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
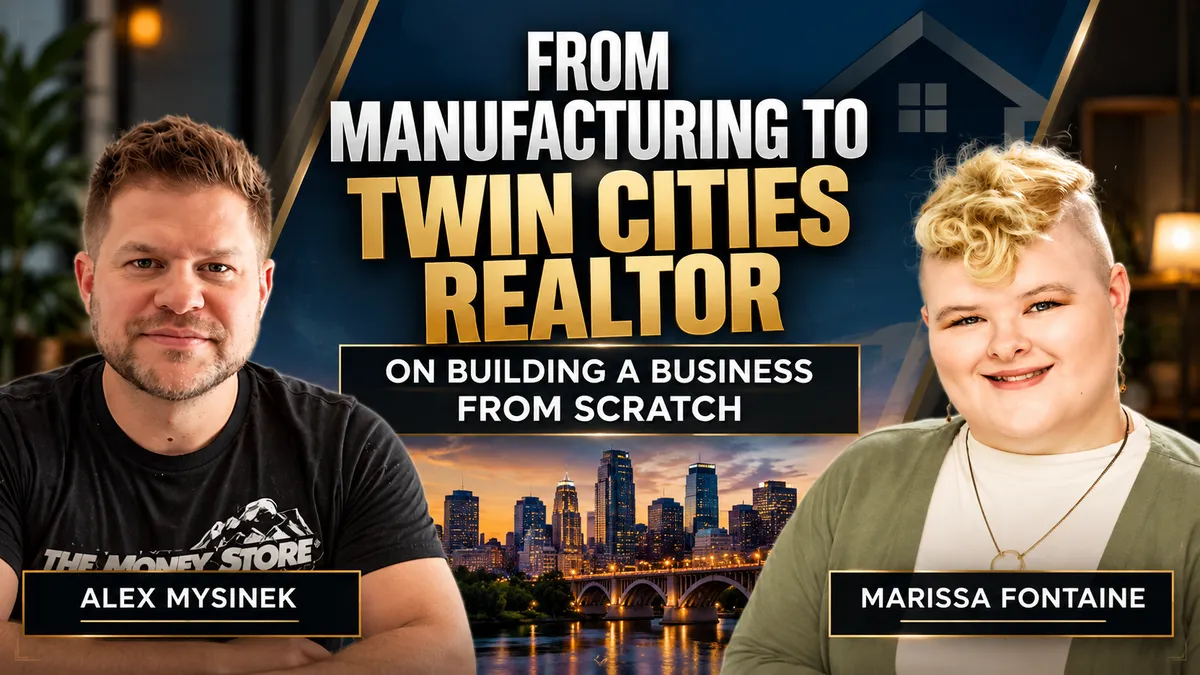
Alex Mysinek Talks Career Change Real Estate Coaching and Twin Cities Market With Marissa Fontaine of Coldwell Banker
The Manufacturing Leader Who Saw a Recruitment Ad and Said I Could Do That
Alex Mysinek welcomed Marissa Fontaine of Coldwell Banker Realty to the podcast for a conversation about what it actually looks like to build a real estate business from scratch after a career in manufacturing, why coaching has been central to her growth, what she gets wrong when she first starts and what she figured out, and how she helps buyers navigate a market where the headlines are louder than the actual opportunity.
Marissa is Twin Cities born and raised and spent most of her professional career working her way into leadership and mentoring roles in manufacturing. She describes herself as someone who needs a solid foundation in whatever she is doing. If the foundation is not good she is not happy. That core characteristic turned out to shape how she approached the career transition, how she built her business, and how she shows up for clients.
How She Made the Transition Without Blowing Up Her Life
The spark was a recruitment ad for real estate that appeared in her Indeed feed while she was still employed in manufacturing. Her reaction was simple and direct. I could do that. Let’s try that. Rather than immediately leaving her stable income she pursued the license and early business development on a dual-career basis until she had enough of a foundation to feel confident in the transition. The same instinct toward solid foundations that defines her personality shaped the career change itself.
Once she made the full move the biggest surprise was realizing she could make real estate completely her own. No mandatory uniform. No requirement to perform a version of herself she did not recognize. She could be exactly who she is and that authenticity turned out to be an asset rather than a liability.
What She Completely Misunderstood Going In
Social media. Marissa acknowledges she did not post at all before getting into real estate and had significantly underestimated what it would take to develop a genuine social media presence. She understood that marketing would be part of the job but the actual work of cultivating a feed, building an audience, and creating content consistently was a different challenge than she expected. She was up for it but it was not on her radar the way it turned out to need to be.
Where Her First Business Came From
Her sphere of influence was the starting point as it is for most agents. Her first transaction was helping her in-laws sell an inherited property. From there she built outward from people who already trusted her. She is direct that what she brought to those early transactions was not years of market experience. It was dynamic thinking, genuine care, and the willingness to work harder than agents who were coasting on their reputation.
Alex connects with this directly from his own experience transitioning from the restaurant industry to mortgage lending. The limiting belief that potential clients will always choose the more experienced option is real and the answer to it is recognizing that a different skill set and a fresher perspective have genuine value that experience alone does not replicate.
Why She Joined a Team and What Coaching Has Given Her
Marissa initially planned to go it alone and then changed course when her coach accepted an invitation to join the Keegley North team. She had already turned down the same invitation. When her coach said yes she called back and took the meeting. The benefits of the team including resources and support have been paying off consistently since.
On coaching specifically Marissa values it primarily for accountability. She knows she is capable of holding herself accountable but having someone else in the conversation who asks why something did not happen and applies consequences for inaction adds a layer of discipline that internal accountability alone cannot fully replicate. Recognition is also meaningful to her and she identifies as a high I on the DISC profile which means external validation and acknowledgment from people she respects genuinely motivates her in ways that are worth building into her professional structure. Alex notes he tested as a high D and high I himself that same day which makes for one of the more fitting coincidences of the episode.
How Being a Twin Cities Native Shows Up in Her Work
Marissa is a level five Google Local Guide for the Minneapolis area which is a meaningful signal about how deeply she engages with local knowledge. She cannot steer clients toward specific neighborhoods and is careful about that boundary. What she can do is translate what buyers tell her they want into an immediate mental picture of where in the Twin Cities that actually exists.
Someone who says they love parks and the Minnehaha area gets a different search than someone who wants to be removed from the city but not completely isolated. A buyer relocating from another state who has no frame of reference gets a conversation about what kind of environment and lifestyle they are looking for before any search is configured. The local knowledge makes those conversations faster and more accurate.
What She Asks Relocating Buyers to Figure Out Where They Should Land
For buyers moving to the Twin Cities from elsewhere Marissa’s first question is always what is driving the move. Career relocation puts the search near the destination. A lifestyle transition opens the conversation to a broader set of questions about what matters most in where they live. Shopping proximity. School quality. Parks and recreational access. Or intentional distance from urban density.
Her follow-up questions are designed to find out which stated requirements are truly non-negotiable and which ones have more flexibility than the buyer initially presents. A three-bedroom requirement often relaxes when she asks whether a two-bedroom with a flex space that could function as a third bedroom would work. A two-thousand square foot minimum often has some give when the layout and light are right. Most people’s hard lines are softer than they think they are and finding that flexibility opens up homes they would otherwise miss in the search.
Her Pre-Approval Rule and Why It Matters
Marissa does not show homes before a buyer has a pre-approval letter. The reason is simple and she states it plainly. She does not want buyers falling in love with something they cannot have before they know what they can actually have.
Alex reinforces this from the lending side with a concrete example. He had just spent time on a call before the podcast helping a buyer understand that the purchase price range they wanted was not achievable at their qualification level and working through what range was realistic. That conversation is much easier before anyone has toured homes than after a buyer has emotionally attached to a property that does not fit their actual budget.
The Rate Conversation She Is Having With Buyers Right Now
When a buyer who was pre-approved at six and a half percent gets an updated approval at seven and a half percent and says they are going to pause the search and rent Marissa’s response is grounded and practical. She does not know what the market will look like in six months but she knows what it looks like right now. And right now the higher rate environment has produced a market where prices are down, sellers are more negotiable, and buyers have leverage they did not have during the frenzy of 2021 and 2022.
Her framing for reluctant buyers is the comparison between the current moment and that period. During the peak buyers were paying one hundred and twenty-five to two hundred thousand dollars over asking price. The purchase price is fixed. The rate is not. Marry the house and date the rate is a phrase that captures something real about the asymmetry between those two variables. A buyer who overpays on purchase price carries that premium in their loan balance indefinitely. A buyer who pays today’s market price at today’s rate can refinance the rate when conditions change but cannot renegotiate the purchase price.
Seller-paid closing costs, price reductions, and the possibility of a seller-funded two-one or one-one buydown add additional tools that make the current market more workable than the headline rate number alone suggests.
What She Looks for in a Lender Partner
Marissa’s answer to what she actually values in a lender goes past the baseline of good communication and loans that close on time. She describes those as the minimum standard that every professional should be meeting not a differentiating characteristic.
What she genuinely values is follow-through. She has had experiences where a lender makes an initial call and then disappears when the first conversation does not immediately produce a transaction. She has had clients come back to her to say the lender she referred them to called once and never answered their questions. That experience reflects badly on her as the referring agent and it serves the client poorly.
The other quality she values is the willingness to explain things at whatever level the client needs without assuming prior knowledge. First time buyers obviously need more explanation but buyers who bought fifteen years ago may be just as unfamiliar with the current process. They might not know what they are doing and their first purchase might have been so rushed through that they never really understood it either. Marissa treats every client as a first timer until the client signals otherwise and she appreciates lenders who operate the same way.
Her Favorite Twin Cities Restaurant
Alex closes every episode with a food question and as a former chef he means it. Marissa’s current favorite is Shinwa in Roseville for Korean barbecue. The grill in the middle, the hot pot, the full experience. Alex is a confirmed sucker for the table-side cooking format in all its variations and both agree that Minnesotans have developed a specific and genuine affection for hibachi and Korean barbecue that is worth acknowledging.
How to Reach Marissa Fontaine
Text, call, email, Facebook DM, or Instagram DM. Marissa is locked into all her channels and responds consistently. Contact information is available through Coldwell Banker Realty in the Twin Cities.
Alex Mysinek handles mortgage financing for buyers throughout Minnesota and is available for pre-approval conversations, rate strategy discussions, and the kind of detailed explanation that makes buyers feel genuinely prepared rather than just processed. Reach out to Alex to connect on the lending side of any Twin Cities transaction.
Sources
MinneapolisAssociationofRealtors.com
NAR.realtor
MortgageNewsDaily.com
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

Social Media Links
YouTube
