Your Local Mortgage Lender
Located in Edina, Minnesota
Personalized Mortgage Experience
Alex Mysinek offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Edina, Minnesota.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
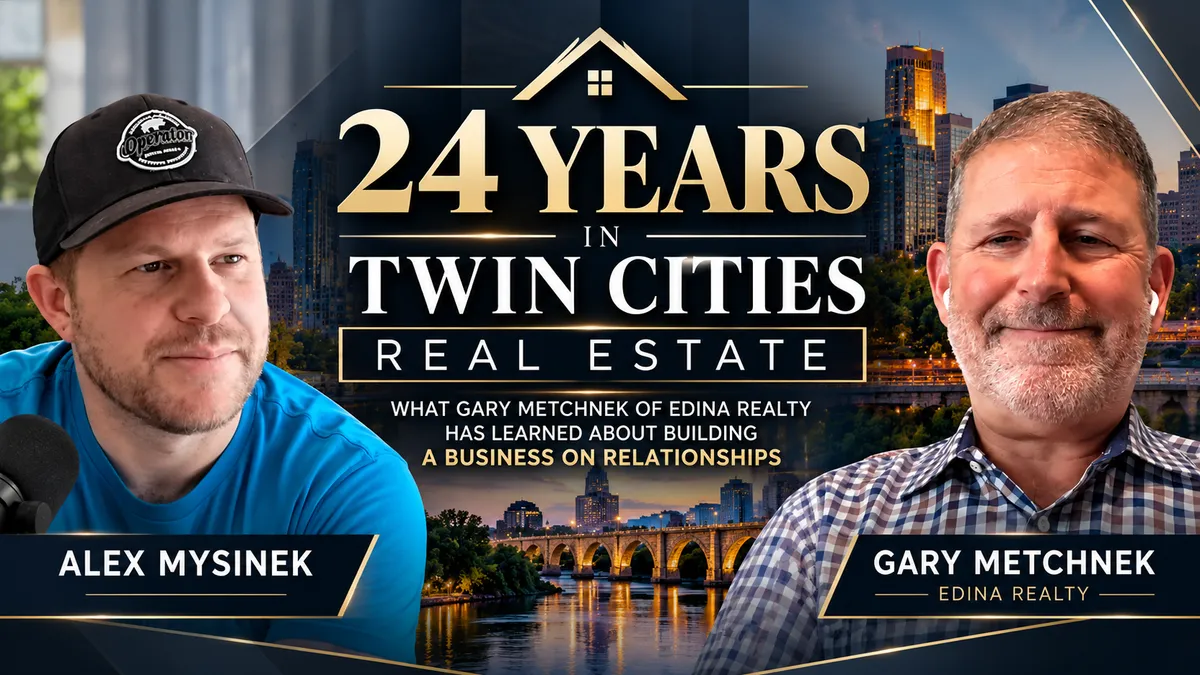
Alex Mysinek Talks 24 Years in Twin Cities Real Estate and Relationship Building With Gary Metchnek of Edina Realty
The Radio Ad Salesman Who Became One of the Twin Cities’ Most Trusted Realtors
Alex Mysinek sat down with Gary Metchnek, realtor with Edina Realty in the Twin Cities, for a conversation about what two decades in residential real estate actually teaches you, how a relationship-first philosophy produces a business built almost entirely on repeat clients and referrals, what Gary is seeing in the Minnesota market right now, and what he genuinely values in a lender partnership.
Gary spent ten years selling radio advertising before the industry consolidated, went corporate, and became something he no longer recognized. He knew how to sell and he knew how to build relationships with people. He just needed a different vehicle. After interviewing with both commercial and residential brokers he chose residential because it fit his personality better. He joined the Edina Realty office he is still in today twenty-four years and approximately eight managers later.
He started with his second child just born, giving up reliable income to start from scratch in a new industry. He hit open houses hard. He networked constantly. He leveraged the sphere he had built over a lifetime of living in the Twin Cities through sports, school, his fraternity, and previous jobs. And he has never paid for a lead.
You Cannot Be a Secret Agent
Gary’s first manager at Edina Realty told him something early on that he has never forgotten. You cannot be a secret agent. Let everyone around you know you are in the business and then actually connect with them as human beings rather than as potential transactions.
The examples he offers are not hypothetical. He has worked with a server he met at a restaurant. He sold a townhome to a nurse who drew his blood at a medical appointment. The common thread is that he is the kind of person who starts conversations and follows through on them. Not with scripts designed to surface real estate intent but with genuine curiosity about the people he meets.
What he does not do is reach out to past clients only when he wants to know if they are thinking about buying or selling. He is direct that people can tell when the only content of a relationship is a check-in designed to generate business. That approach does not build trust. It erodes it.
What He Actually Does to Stay Connected
Gary’s database management is less systematized than some and more human than most. He scrolls through his contacts regularly and reaches out to people he has not talked to in a while. He remembers the dogs and cats by name because he is a genuine animal lover and because that kind of detail signals to clients that the relationship they have with him is real. He takes clients to games when he has tickets. He takes people to lunch. He sends mailings a couple of times a year with sports schedules and small gifts that have actual value rather than branded tchotchkes nobody keeps.
He learned the gift lesson from a business partner who has been in real estate twenty-five years longer than Gary and who has always sent things people actually use and talk about. Not because of the dollar amount but because the thought behind them is evident. Clients remember him specifically for the gifts while forgetting everything else the market sent them.
Alex shares that he uses a service called Client Giant for the first year after every closing, sending four curated gifts to each client on a schedule. The philosophy is the same as Gary’s. If you are going to spend the money make it something that lands rather than something that gets thrown away.
The stat Alex raises is worth sitting with. Ninety-one percent of realtors never reach out to their past clients. Gary has seen that number and is not surprised. The agents who do reach out consistently and authentically do not have to fight nearly as hard for new business because the clients they already have keep sending people to them.
What Gary Is Seeing in the Twin Cities Market Right Now
The word Gary reaches for is bifurcated and he is not wrong. The Minnesota market this year has split in a way he has not seen before. Some properties are moving immediately with multiple offers in the first weekend. Others that are reasonably priced and in decent condition are sitting significantly longer than anything sat two or three years ago when the market was on fire.
The determining factors are preparation, marketing, photography, and pricing. The homes generating immediate activity are the ones where sellers and their agents did everything right to present the property to the market. The homes sitting are the ones where one or more of those things was missed. The gap between the two outcomes is wider than it has been in years and the uncertainty about which camp a given listing will land in makes the pre-market preparation conversation more important than ever.
Alex is seeing significant seller-paid closing costs coming through on his lending side which he reads as a clear sign the market has cooled from its peak. When sellers were receiving fifteen and twenty offers nobody was paying closing costs. The fact that they are now tells you where the leverage has shifted.
What Gary Looks for in a Lender Partner
Gary’s answer is not about technology or rate sheets. It is about trust.
He wants to refer his buyers to a lender and then largely not hear about problems until closing because the transaction is being handled well behind the scenes. He has worked with lenders who constantly needed something from him or from the buyer at inconvenient times and he has worked with lenders who make the entire process feel seamless. The difference is not luck. It is how meticulous the lender is at the front end.
He validates something Alex describes about his own process. Collecting everything from the borrower upfront before any contract is signed means that when the buyer does go under contract they are not being buried in document requests at the exact moment they are also hearing from the title company, the inspector, the seller’s agent, and everyone else involved in the transaction. Getting ahead of the paperwork is not about being difficult. It is about protecting the buyer from overwhelm at the worst possible time.
Gary says something he has told buyers directly. You are going to get sick of the lender asking for documents. Trust them. They are doing this now so closing goes smoothly.
He also values lenders who show up to closings. Not because it is always possible but because having the lending professional in the room when a wire is delayed or a last-minute question surfaces is the difference between a solvable problem and a panicked phone tree experience that nobody wants to have at the closing table.
The Fatal Flaw Conversation
One of the most useful things Gary does for buyers that newer agents sometimes skip is the fatal flaw conversation. He will tell a buyer directly when a property has a characteristic that will make it hard to sell later regardless of how much they love it now. Train tracks. A problematic neighboring property. A busy road that becomes impossible to ignore once you live there. Buyers in the excitement of imagining their furniture placement are not always paying attention to these things. That is exactly why they hired a fiduciary who is.
He would rather have a difficult conversation before the offer than watch a client struggle to sell a house with an unavoidable drawback in a tough future market.
How to Reach Gary Metchnek
Call or text 612-237-3276. Visit GaryMetchnek.com. The last name is spelled M-E-T-C-H-N-E-K. Phone, text, email, or smoke signal according to Gary. He works with residential buyers and sellers and investment properties throughout the Twin Cities.
Alex Mysinek works with buyers throughout Minnesota on mortgage financing. Reach out to Alex for pre-approval and lending support on any Twin Cities transaction.
Sources
MinneapolisAssociationofRealtors.com
NAR.realtor
MortgageNewsDaily.com
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

Social Media Links
YouTube
